2026 Income Tax Guide for LLCs and Freelancers: Tax Rates, Deductions and Deadlines
A freelancer can earn $80,000 from clients during 2026 and still be unsure how much should be reserved for federal income tax, self-employment tax, state tax, and estimated payments.
An LLC owner can face a similar problem. Forming an LLC creates a legal business structure, but an LLC does not automatically receive its own federal income-tax rate. For federal tax purposes, an LLC may be treated as a disregarded entity, partnership, S corporation, or C corporation depending on its ownership and elections.
That distinction matters throughout 2026.
Your actual tax bill depends on factors such as business profit, filing status, deductions, credits, other household income, withholding, business structure, and state. A freelancer may owe both federal income tax and self-employment tax. An LLC owner may have pass-through income rather than a separate federal income-tax bill at the entity level.
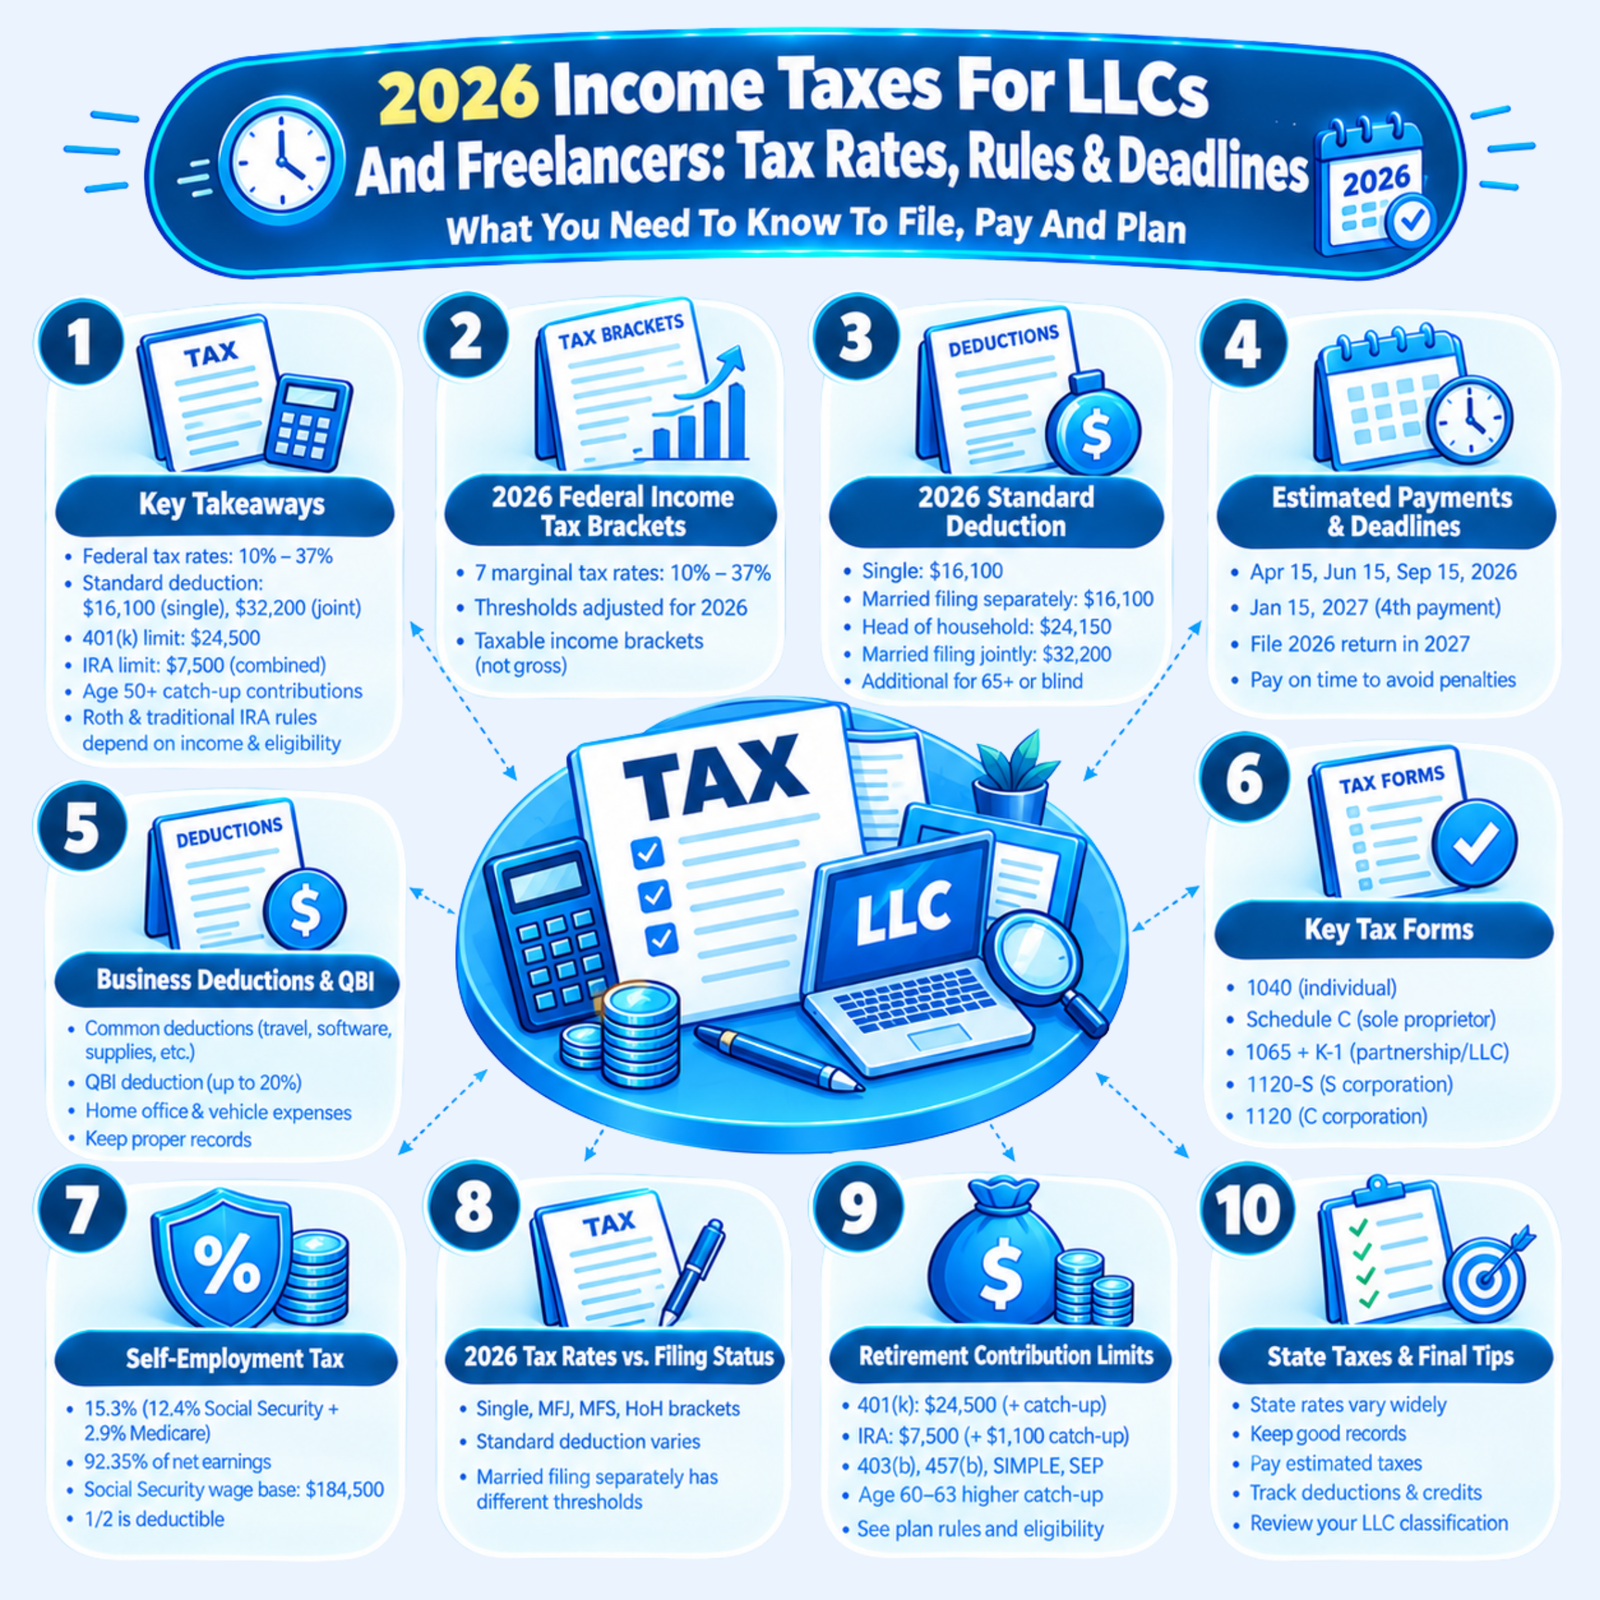
This article explains the major 2026 income-tax rules freelancers and LLC owners need to understand, including tax brackets, estimated payments, deductions, QBI, tax forms, deadlines, and recordkeeping.
Tax-year note: The 2026 tax year covers income earned from January 1 through December 31, 2026. A federal return reporting that income will generally be filed in 2027. A return filed during 2026 generally relates to 2025 income.
Key 2026 Income Tax Facts For LLCs And Freelancers
| Tax Topic | What It Means |
| Federal income tax | Tax on taxable income after applicable deductions and adjustments |
| Self-employment tax | Social Security and Medicare taxes that generally apply to net earnings from self-employment |
| Estimated tax | Periodic payments toward expected federal tax liability |
| State income tax | State-level income tax where applicable |
| Business deductions | Eligible business expenses that can reduce business profit |
| QBI deduction | Potential deduction for qualifying pass-through business income |
| Tax credits | Amounts that can directly reduce tax liability when eligibility requirements are met |
The most important point is that these taxes do not necessarily apply in the same way to every taxpayer.
For example, a sole proprietor may report business income on Schedule C and calculate self-employment tax on Schedule SE. An LLC taxed as an S corporation has a different federal filing structure and payroll responsibilities.
What Does “2026 Income Tax” Actually Mean?
The phrase 2026 income taxes can mean several different things, so separating the dates is essential.
Tax year 2026
The 2026 tax year covers:
January 1, 2026 → December 31, 2026
Business revenue, deductible expenses, investment income, wages, and other taxable items earned or incurred during this period generally belong to the 2026 tax year.
2026 filing season
A return filed during 2026 generally reports 2025 income.
For example:
-
- Income earned in 2025 → generally reported on the return filed in 2026
- Income earned in 2026 → generally reported on the return filed in 2027
Estimated payments
Estimated payments for 2026 are made during 2026, with the final regular estimated payment generally due in January 2027.
2026 tax return
A calendar-year individual generally files the federal return for 2026 in 2027.
The practical timeline is:
January 1 – December 31, 2026: Earn income and incur business expenses
Throughout 2026: Track income, expenses, and tax payments
April, June, September 2026 + January 2027: Make required estimated payments
Early 2027: Prepare the 2026 return
April 2027: File the 2026 individual return and pay any remaining balance, subject to applicable deadlines and extensions
What Are The Federal Income Tax Brackets For 2026?
The United States uses a marginal tax system.
This means your income is divided into layers. Moving into a higher bracket does not mean your entire income is suddenly taxed at the higher rate.
For 2026, the seven federal individual income-tax rates remain:
10%, 12%, 22%, 24%, 32%, 35%, and 37%.
2026 tax brackets for single taxpayers
| Taxable Income | Federal Rate |
| 0–12,400 | 10% |
| 12,400–50,400 | 12% |
| 50,400–105,700 | 22% |
| 105,700–201,775 | 24% |
| 201,775–256,225 | 32% |
| 256,225–640,600 | 35% |
| Over $640,600 | 37% |
2026 tax brackets for married filing jointly
| Taxable Income | Federal Rate |
| 0–24,800 | 10% |
| 24,800–100,800 | 12% |
| 100,800–211,400 | 22% |
| 211,400–403,550 | 24% |
| 403,550–512,450 | 32% |
| 512,450–768,700 | 35% |
| Over $768,700 | 37% |
2026 tax brackets for married filing separately
| Taxable Income | Federal Rate |
| 0–12,400 | 10% |
| 12,400–50,400 | 12% |
| 50,400–105,700 | 22% |
| 105,700–201,775 | 24% |
| 201,775–256,225 | 32% |
| 256,225–384,350 | 35% |
| Over $384,350 | 37% |
2026 tax brackets for head of household
| Taxable Income | Federal Rate |
| 0–17,700 | 10% |
| 17,700–67,450 | 12% |
| 67,450–105,700 | 22% |
| 105,700–201,750 | 24% |
| 201,750–256,200 | 32% |
| 256,200–640,600 | 35% |
| Over $640,600 | 37% |
These brackets apply to taxable income, not simply gross freelance revenue.
How Marginal Taxation Works
Suppose a single taxpayer has $70,000 of taxable income.
That does not mean the entire $70,000 is taxed at 22%.
Instead:
-
- The first $12,400 is in the 10% layer.
- The next portion is taxed at 12%.
- Only the taxable income above $50,400 enters the 22% bracket.
This is why saying “I am in the 22% bracket” does not mean the taxpayer pays 22% of all income in federal income tax.
2026 Standard Deduction Amounts
For tax year 2026, the standard deduction is:
| Filing Status | 2026 Standard Deduction |
| Single | $16,100 |
| Married filing separately | $16,100 |
| Married filing jointly | $32,200 |
| Qualifying surviving spouse | $32,200 |
| Head of household | $24,150 |
Additional standard-deduction amounts may apply to taxpayers who are age 65 or older or blind.
The standard deduction reduces income used to calculate federal income tax. It is separate from legitimate business deductions.
For example, a freelancer can generally:
-
- Calculate business revenue.
- Deduct eligible business expenses.
- Determine net business profit.
- Report that business income on the appropriate tax return.
- Potentially claim the standard deduction or itemized deductions on the individual return.
Claiming business expenses does not automatically prevent a taxpayer from taking the standard deduction.
How Are Freelancers Taxed In 2026?
A freelancer operating as a sole proprietor generally starts with business revenue and subtracts eligible business expenses to determine net profit.
A simplified flow looks like this:
Gross freelance revenue
↓
Minus deductible business expenses
↓
Net business profit
↓
Self-employment tax calculation
↓
Adjustments and other deductions
↓
Taxable income
↓
Federal income tax + applicable other taxes
↓
Credits and payments
↓
Balance due or refund
Freelance income may be reported on a Form 1099-NEC, Form 1099-K, Form 1099-MISC, direct payments, or other records. Receiving no 1099 does not generally mean the income can be ignored.
A freelancer should track the actual income received or otherwise reportable under the applicable tax rules, rather than relying solely on information returns received from clients.
What Is Self-Employment Tax In 2026?
Self-employment tax is different from federal income tax.
It generally covers the Social Security and Medicare taxes that apply to people who work for themselves.
For 2026, the self-employment tax rate is generally 15.3%, consisting of:
-
- 12.4% Social Security
- 2.9% Medicare
The calculation generally begins with 92.35% of net earnings from self-employment, rather than simply applying 15.3% to every dollar of gross revenue.
For 2026, the Social Security taxable maximum is $184,500.
There is no general Social Security wage-base limit for the Medicare portion.
Simplified Self-Employment Tax Example
Suppose a freelancer has:
-
- $80,000 of business profit
- No other self-employment income
- No wages affecting the Social Security wage-base calculation
A simplified starting point would be
$80,000 × 92.35% = $73,880
The Social Security and Medicare portions are then calculated under the Schedule SE rules.
This is only a simplified illustration. A real return can produce a different result depending on wages, other self-employment income, additional Medicare tax, and other factors.
Half of the self-employment tax is generally allowed as an adjustment to income.
How Much Should A Freelancer Set Aside For Taxes?
There is no percentage that works for every freelancer.
You may see advice telling freelancers to save 25%, 30%, or 40% of income. Those percentages can be useful as personal budgeting rules, but they are not federal tax rates.
Your actual tax burden can depend on:
-
- Business profit
- Filing status
- Federal tax brackets
- Self-employment tax
- Business deductions
- QBI deduction
- Tax credits
- Other household income
- W-2 withholding
- Estimated tax payments
- State and local taxes
- Other deductions and adjustments
A freelancer earning $80,000 with $20,000 of legitimate business expenses is in a different position from someone earning $80,000 with almost no business expenses.
A practical approach is to:
-
- Track revenue monthly.
- Track deductible expenses monthly.
- Estimate annual profit.
- Estimate federal income tax and self-employment tax.
- Add applicable state tax.
- Subtract expected withholding and estimated payments.
- Update the calculation whenever income changes materially.
2026 Estimated Tax Payments For Freelancers
The federal tax system generally operates on a pay-as-you-go basis.
If you earn income that does not have sufficient withholding, you may need to make estimated tax payments.
For most individuals, the IRS generally requires estimated payments when both of these conditions apply:
-
- You expect to owe at least $1,000 after subtracting withholding and refundable credits.
- Your withholding and refundable credits are less than the smaller of 90% of your expected 2026 tax or 100% of the tax shown on your 2025 return, subject to special rules.
Taxpayers generally must use 110% of their prior-year tax for the prior-year safe-harbor calculation if their prior-year adjusted gross income exceeded $150,000 ($75,000 for married taxpayers filing separately). Other taxpayers generally use 100%, subject to the applicable IRS rules.
2026 estimated tax payment dates
| Payment | Due Date |
| First payment | April 15, 2026 |
| Second payment | June 15, 2026 |
| Third payment | September 15, 2026 |
| Fourth payment | January 15, 2027 |
The January 15, 2027 payment generally is not required if the taxpayer files the 2026 return by February 1, 2027 and pays the full balance due.
Estimated payments do not necessarily have to be four identical amounts. If income is uneven during the year, the annualized income installment method may help match payments more closely to when income is earned.
2026 Tax Deadlines For Freelancers And LLC Owners
Different business structures have different filing dates.
For calendar-year taxpayers, the major deadlines associated with 2026 income generally fall in 2027.
| Deadline | What It Relates To | Who It May Affect |
| Jan. 15, 2027 | Fourth 2026 estimated tax payment | Individuals making estimated payments |
| Mar. 15, 2027 | Partnership/S corporation returns | Calendar-year Form 1065 and Form 1120-S filers |
| Apr. 15, 2027 | Individual federal return | Calendar-year Form 1040 filers |
| Apr. 15, 2027 | C corporation return | Calendar-year C corporations |
| Sept. 15, 2027 | Extended partnership/S corporation deadline | Eligible calendar-year filers |
| Oct. 15, 2027 | Extended individual return deadline | Eligible individual filers |
An extension generally extends the time to file, not the time to pay.
If you expect to owe tax, you generally need to pay the estimated balance by the original payment deadline even if you request an extension to file.
How Are LLCs Taxed In 2026?
An LLC does not have one universal federal income-tax rate.
This is one of the most important concepts for new LLC owners.
An LLC is a state-law business entity. For federal income-tax purposes, the IRS looks at the LLC’s classification.
The main possibilities are:
| LLC Structure | Typical Federal Tax Treatment | Common Federal Return |
| Single-member LLC | Disregarded entity by default | Owner’s return, often Schedule C |
| Multi-member LLC | Partnership by default | Form 1065 + Schedule K-1 |
| LLC taxed as S corporation | S corporation taxation | Form 1120-S + Schedule K-1 |
| LLC taxed as C corporation | Corporate taxation | Form 1120 |
This is a simplified overview. Elections, ownership changes, special circumstances, and state rules can alter filing requirements.
Single-Member LLC Taxes In 2026
A domestic single-member LLC is generally treated as a disregarded entity for federal income-tax purposes unless the owner makes an election to have it taxed differently.
For an owner operating an active trade or business, the business activity commonly flows onto the owner’s federal return, often through Schedule C.
The owner may therefore have:
-
- Federal income tax
- Self-employment tax
- Estimated tax obligations
- Business deductions
- Potential QBI deduction
- State and local tax obligations
Forming the LLC does not, by itself, create a special lower federal income-tax rate.
This is why comparing “LLC taxes” with “freelancer taxes” can be misleading. A single-member LLC can have substantially the same federal income-tax treatment as a sole proprietorship unless a different tax election is made.
Multi-Member LLC Taxes In 2026
A domestic LLC with two or more members generally defaults to partnership treatment for federal income-tax purposes.
The partnership generally files:
Form 1065 – US Return of Partnership Income
The business generally provides each partner with:
Schedule K-1
The partnership generally does not operate like a traditional C corporation where the corporation pays federal income tax on its taxable income and then shareholders may pay tax on dividends.
Instead, partnership income generally passes through to the partners, who report their applicable shares on their own returns.
Partners may also have self-employment tax obligations depending on the nature of the income and their role in the partnership.
LLC Taxed As An S Corporation In 2026
An eligible LLC can elect to be taxed as an S corporation.
An S corporation generally files:
Form 1120-S
Shareholders generally receive:
Schedule K-1
One reason business owners consider S corporation taxation is the different treatment of wages and distributions. An owner who works for the S corporation generally must receive reasonable compensation subject to applicable payroll taxes before taking distributions.
That does not mean every freelancer should elect S corporation taxation.
The decision should account for:
-
- Business profit
- Reasonable compensation
- Payroll costs
- Payroll-tax savings, if any
- Accounting costs
- State taxes
- Compliance costs
- Administrative workload
- Retirement-plan considerations
- The owner’s broader tax situation
A rule such as “form an S corporation once you earn $X” is too simplistic to apply universally.
C Corporation Taxation For LLC Owners
An LLC can elect corporate tax treatment and, depending on the election, may be taxed as a C corporation.
A C corporation generally files:
Form 1120
The corporation generally pays federal corporate income tax on its taxable income.
If after-tax corporate earnings are distributed to shareholders as dividends, those distributions can create a separate tax consequence for the shareholders.
This potential two-level taxation is commonly called double taxation.
C corporation treatment can make sense for some businesses, particularly businesses with particular investment, ownership, financing, or growth objectives, but it is usually not the default tax structure considered by a solo freelancer.
2026 Business Tax Deductions For Freelancers And LLCs
Business deductions can reduce taxable business profit when the expenses meet the applicable requirements.
Common categories can include:
| Expense Category | Examples |
| Advertising | Digital advertising, promotional campaigns |
| Software | Design, accounting, project-management software |
| Professional services | Attorneys, accountants, consultants |
| Website costs | Hosting, domains, qualifying development costs |
| Insurance | Certain business insurance premiums |
| Office expenses | Supplies and qualifying office costs |
| Travel | Qualifying business travel |
| Contractors | Payments to independent contractors |
| Education | Qualifying education that maintains or improves business skills |
| Banking/payment fees | Business account and payment-processing fees |
| Phone/internet | Qualifying business-use portion |
| Home office | Qualifying home-office expenses |
A business expense is not deductible merely because it is helpful.
The expense generally must satisfy the applicable tax rules, and personal expenses cannot simply be relabeled as business expenses.
Good documentation should establish both:
- What was purchased
- Why it was a business expense
Home Office Deduction In 2026
Working from home does not automatically qualify someone for a home-office deduction.
Generally, the applicable space must satisfy requirements such as regular and exclusive business use, along with the other IRS qualification rules.
Eligible taxpayers may generally choose between:
Simplified Method
A prescribed rate is applied to qualifying square footage, subject to the applicable maximum.
Actual-Expense Method
The taxpayer calculates the qualifying portion of actual household expenses under the IRS rules.
Examples of potentially relevant costs can include:
-
- Rent
- Mortgage interest
- Utilities
- Insurance
- Repairs
- Depreciation
The method selected can affect the calculation and recordkeeping requirements.
Vehicle And Travel Expenses
Freelancers frequently use vehicles for business, but personal driving and business driving must be separated.
For 2026, the IRS standard mileage rate for business use is 72.5 cents per mile from January 1 through June 30, 2026, and 76 cents per mile from July 1 through December 31, 2026. Freelancers should use the rate that applies to the date the business mileage was driven.
A taxpayer may instead qualify to use the actual-expense method.
Mileage records should generally include information such as:
-
- Date
- Destination
- Business purpose
- Business miles
Commuting between a taxpayer’s home and regular workplace is generally treated differently from qualifying business travel.
Travel away from the taxpayer’s tax home can involve additional rules concerning transportation, lodging, meals, and business purpose.
2026 QBI Deduction For Freelancers And Pass-Through Businesses
The Qualified Business Income (QBI) deduction can provide a deduction for qualifying business income.
The deduction is generally associated with eligible pass-through businesses, including many sole proprietorships, partnerships, and S corporations.
The basic concept is often described as a deduction of up to 20% of qualified business income, but that does not mean every freelancer automatically receives a 20% deduction.
The calculation can depend on:
-
- Taxable income
- Type of business
- W-2 wages
- Qualified property
- Qualified business income
- Filing status
- Specified service trade or business rules
- Other limitations
For 2026, the QBI threshold amounts are:
| Filing Status | Threshold | Phase-In Range Ends |
| Married filing jointly | $403,500 | $553,500 |
| Married filing separately | $201,775 | $276,775 |
| Other returns | $201,750 | $276,750 |
The QBI deduction was made permanent under current law.
For taxpayers within or above the relevant thresholds, the calculation can become significantly more complicated, particularly for specified service businesses.
What Is The Difference Between Taxable Income And Business Profit?
These terms are not interchangeable.
Consider a simplified example:
Freelance revenue: $100,000
Eligible business expenses: $25,000
Net business profit: $75,000
The $75,000 is the business profit before considering other individual-level adjustments and deductions.
It is not necessarily the taxpayer’s final taxable income.
The taxpayer may also have:
-
- W-2 income
- Investment income
- Retirement deductions
- The deductible portion of self-employment tax
- QBI deduction
- Standard or itemized deductions
- Tax credits
- Other adjustments
A simplified flow is:
$100,000 revenue
→ $25,000 business expenses
→ $75,000 business profit
→ individual adjustments/deductions
→ taxable income
How To Calculate Taxes On Freelance Income
A practical calculation generally follows these steps:
1. Add business Revenue
Include income from clients, platforms, contracts, and other business sources.
2. Subtract Eligible Business Expenses
Remove qualifying ordinary and necessary business expenses under the applicable rules.
3. Calculate Net Business Profit
This is the key starting point for many self-employment calculations.
4. Calculate Self-Employment Tax
Use Schedule SE and the applicable 2026 rules.
5. Calculate Adjusted Gross Income
Account for applicable adjustments, including the deductible portion of self-employment tax.
6. Determine Taxable Income
Apply the standard deduction or itemized deductions and other applicable deductions.
7. Calculate Federal Income Tax
Apply the appropriate tax brackets and any applicable special tax rules.
8. Apply Credits
Eligible tax credits can reduce the tax liability.
9. Add State And Local Taxes
These depend on where the taxpayer lives, works, and conducts business.
10. Subtract Payments Already Made
Account for:
-
- Federal withholding
- Estimated tax payments
- Applicable refundable credits
The result may be a balance due or a refund.
Federal Income Tax vs Self-Employment Tax vs State Tax
| Tax | What It Generally Applies To | Who May Owe It |
| Federal income tax | Taxable income | Individuals and business owners |
| Self-employment tax | Net earnings from self-employment | Eligible self-employed individuals |
| State income tax | State taxable income | Depends on state |
| Local tax | Local income or business activity | Depends on jurisdiction |
These taxes should not be treated as one combined tax.
For example, a freelancer can owe federal income tax and self-employment tax on the same underlying business activity.
What Tax Forms Do Freelancers Need In 2026?
The forms used depend on the business structure.
| Form | Purpose | Who May Use It |
| Form 1040 | Individual federal income-tax return | Individuals |
| Schedule C | Business income and expenses | Sole proprietors and applicable single-member LLC owners |
| Schedule SE | Self-employment tax | Eligible self-employed individuals |
| Form 1040-ES | Estimated tax | Individuals making estimated payments |
| Form 1065 | Partnership return | Multi-member LLCs taxed as partnerships |
| Schedule K-1 | Pass-through income information | Partners/shareholders |
| Form 1120-S | S corporation return | S corporations |
| Form 1120 | C corporation return | C corporations |
| Form 2553 | S corporation election | Eligible entities making an S election |
| Form 8995 | QBI deduction | Eligible taxpayers with qualifying income |
| Form 8995-A | More complex QBI calculations | Taxpayers subject to additional QBI calculations |
Other forms may apply depending on employees, contractors, foreign transactions, assets, retirement plans, or other circumstances.
2026 Tax Deductions vs Tax Credits
A tax deduction generally reduces the amount of income subject to tax.
A tax credit generally reduces the tax itself.
For example, suppose a taxpayer has $60,000 of income and qualifies for a $5,000 deduction.
A simplified illustration would reduce taxable income by $5,000.
A $5,000 tax credit, by contrast, could reduce the calculated tax liability by $5,000 if the credit is fully usable.
Credits have their own eligibility, refundability, phaseouts, and other rules, so a $5,000 deduction and $5,000 credit are not economically equivalent.
What Records Should Freelancers Keep For 2026 Taxes?
A freelancer should maintain records throughout the year instead of attempting to reconstruct everything during filing season.
Income records
-
- Client invoices
- Payment records
- Bank statements
- Payment-platform statements
- 1099-NEC forms
- 1099-K forms
- 1099-MISC forms
- Other business income records
Expense records
-
- Receipts
- Invoices
- Software subscriptions
- Advertising invoices
- Contractor invoices
- Professional-service bills
- Business insurance records
- Travel records
- Mileage logs
- Home-office records
- Equipment purchases
- Payment-processing fees
- Business bank statements
Tax-payment records
Keep records of:
-
- Estimated tax payments
- Federal withholding
- State tax payments
- Tax return payments
- Refunds or credits carried forward
Bank statements are useful, but a bank transaction alone may not explain the business purpose of an expense.
What Happens If A Freelancer Does Not Pay Estimated Taxes?
If a taxpayer was necessary to make estimated payments & did not pay sufficient or paid late, an underpayment penalty may apply.
The exact calculation depends on factors such as
-
- Amount underpaid
- When the payment should have been made
- When the payment was actually made
- Tax liability
- Applicable safe-harbor rules
- Special circumstances
Estimated tax rules exist because federal income tax is generally paid as income is earned.
If income increases significantly during the year, the freelancer should revisit estimated payments instead of waiting till the following year’s filing deadline
State Income Taxes for Freelancers And LLCs In 2026
Federal rules are only one part of the picture.
State taxation varies considerably.
Depending on the state and the taxpayer’s circumstances, a freelancer or LLC owner may encounter
-
- Individual income tax
- Business income tax
- Franchise taxes
- Annual LLC fees
- Minimum business taxes
- Gross-receipts taxes
- Sales tax obligations
- Employer taxes
- Local taxes
Some states do not impose a broad individual income tax, but that does not mean every business operating there is free from all state taxes or fees.
Likewise, creating an LLC in a state with no individual income tax does not automatically eliminate tax obligations in another state where the owner lives or conducts business.
State nexus rules can become especially important for remote businesses and online companies.
Are LLC Taxes Different From Freelancer Taxes?
The simplest answer is:
Not necessarily.
The important difference is usually the business’s federal tax classification, not the word “LLC.”
| Business Situation | Typical Federal Treatment |
| Freelancer/sole proprietor | Business income generally reported on individual return |
| Single-member LLC | Usually disregarded entity by default |
| Multi-member LLC | Partnership by default |
| LLC taxed as S corporation | S corporation tax treatment |
| LLC taxed as C corporation | Corporate tax treatment |
A single-member LLC can therefore have a federal tax calculation that looks very similar to that of a sole proprietor.
2026 Tax Example For A Freelancer
Consider this hypothetical freelancer:
Freelance revenue: $90,000
Qualifying business expenses: $20,000
Net business profit: $70,000
The simplified flow is:
$90,000 revenue
− $20,000 eligible expenses
= $70,000 net business profit
The freelancer would then calculate applicable self-employment tax using Schedule SE.
The deductible portion of self-employment tax would affect adjusted gross income.
The freelancer would then determine taxable income after applicable deductions, including the standard deduction if eligible, and calculate federal income tax using the 2026 brackets.
If eligible, the taxpayer would also consider the QBI deduction.
Finally, the taxpayer would account for:
-
- Federal estimated payments
- W-2 withholding, if any
- Applicable tax credits
- State income tax
- Other applicable taxes
This is intentionally simplified. It is not a substitute for a complete 2026 tax calculation.
Official Resources
IRS 2026 Federal Tax Brackets and Standard Deductions
IRS Tax Guide for Small Business
IRS LLC Federal Tax Classification
IRS 2026 Standard Mileage Rates
IRS Qualified Business Income Deduction
IRS Forms, Instructions, and Publications
US Small Business Administration Launch Your Business
Frequently Asked Questions
What are the federal income tax rates for 2026?
The federal individual income-tax rates for 2026 are 10%, 12%, 22%, 24%, 32%, 35%, and 37%. The rate applied depends on taxable income and filing status. The system is marginal, so entering a higher bracket does not cause all income to be taxed at that rate.
When are 2026 estimated tax payments due?
The regular 2026 estimated-payment dates are April 15, June 15, and September 15, 2026, followed by January 15, 2027 for the fourth payment.
How are single-member LLCs taxed in 2026?
A domestic single-member LLC generally receives disregarded-entity treatment by default for federal income-tax purposes unless the owner elects another classification. Business activity commonly flows onto the owner’s individual return, often through Schedule C.
Do LLCs have their own federal income tax rate?
No single federal income-tax rate applies to all LLCs. The federal treatment depends on the LLC’s classification, such as disregarded entity, partnership, S corporation, or C corporation.
What deductions can freelancers claim in 2026?
Potential deductions include qualifying advertising, software, professional services, business insurance, supplies, contractor costs, business travel, qualifying education, business-use phone and internet, payment-processing fees, and qualifying home-office expenses. The expense must satisfy the applicable tax rules.
Can freelancers deduct home-office expenses in 2026?
A freelancer may qualify if the applicable IRS requirements are met. Regular and exclusive business use is an important requirement, although other rules also apply. Eligible taxpayers may generally use the simplified or actual-expense method.
Is an LLC better for taxes than being a sole proprietor?
Not automatically. A single-member LLC generally receives the same default federal income-tax treatment as a sole proprietorship unless another tax classification is elected. The advantages of an LLC can extend beyond federal income taxes.
When should a freelancer consider S corporation taxation?
There is no universal income level at which an S corporation automatically becomes the better choice. The decision should consider profit, reasonable compensation, payroll costs, administrative requirements, state taxes, professional fees, and the potential tax benefits.
2026 Income Taxes for LLCs and Freelancers
Understand 2026 federal tax brackets, self-employment taxes, LLC tax classifications, business deductions, estimated payments, and filing deadlines. Learn how tax rules apply to freelancers and LLC owners and what to consider when planning your taxes.
Get 2026 Tax Guidance